TSP to Gold IRA: How a TSP Rollover Works Under TSP Rules
How to move Thrift Savings Plan money into a gold IRA under current TSP rules: who's eligible, the online request, spousal consent, Roth money, and pitfalls.
Published Facts last checked
This is an independently operated affiliate website. We may receive compensation if you contact or become a customer of Augusta Precious Metals through links or phone numbers on this site. How this site is funded.
The Thrift Savings Plan lets eligible federal employees and uniformed services members roll money into an IRA, including a self-directed IRA whose custodian holds physical gold and silver. The TSP has its own rules for who can move money, how the request is made, and what spouses must sign, and they differ in several ways from a private-sector 401(k). This page walks through those rules using the TSP's own publications, most of them updated in 2026.
It explains the mechanics only. Whether to move TSP savings into precious metals, and how much, is a decision to make with a licensed financial or tax professional who knows your situation.
Who Can Move TSP Money
There are two routes, and which one applies depends on whether you're still in federal service:
| Your situation | Route | Key TSP rules |
|---|---|---|
| Separated from federal service | Post-separation withdrawal or distribution | Request in My Account or through the ThriftLine; partial distributions must be at least $1,000 |
| Still employed, age 59½ or older | Age-based in-service withdrawal | Up to four per calendar year; at least $1,000 or your entire vested balance |
| Still employed, under 59½ | No rollover route | Under IRS rules, hardship distributions can't be rolled over to an IRA |
Two details catch people out after separation. If you're rehired into federal service with a break of less than 31 full calendar days, the TSP says you're not eligible to take distributions. And the TSP warns that it can sometimes take up to 30 days for your agency or service to report your separation date, so you may have to wait before you can request anything.
The TSP used to require a 30-day wait between withdrawal requests. That rule ended on May 15, 2024.
How the Request Works
The TSP no longer handles this on paper withdrawal forms. Versions of forms such as the TSP-70, TSP-75, and TSP-77 dated before September 2019 are obsolete, the TSP's current forms page doesn't list them, and its current guidance is to "request a rollover in My Account or by using one of the ThriftLine options." It adds: "Do not use forms provided by the new plan or financial institution."
In practice, that means:
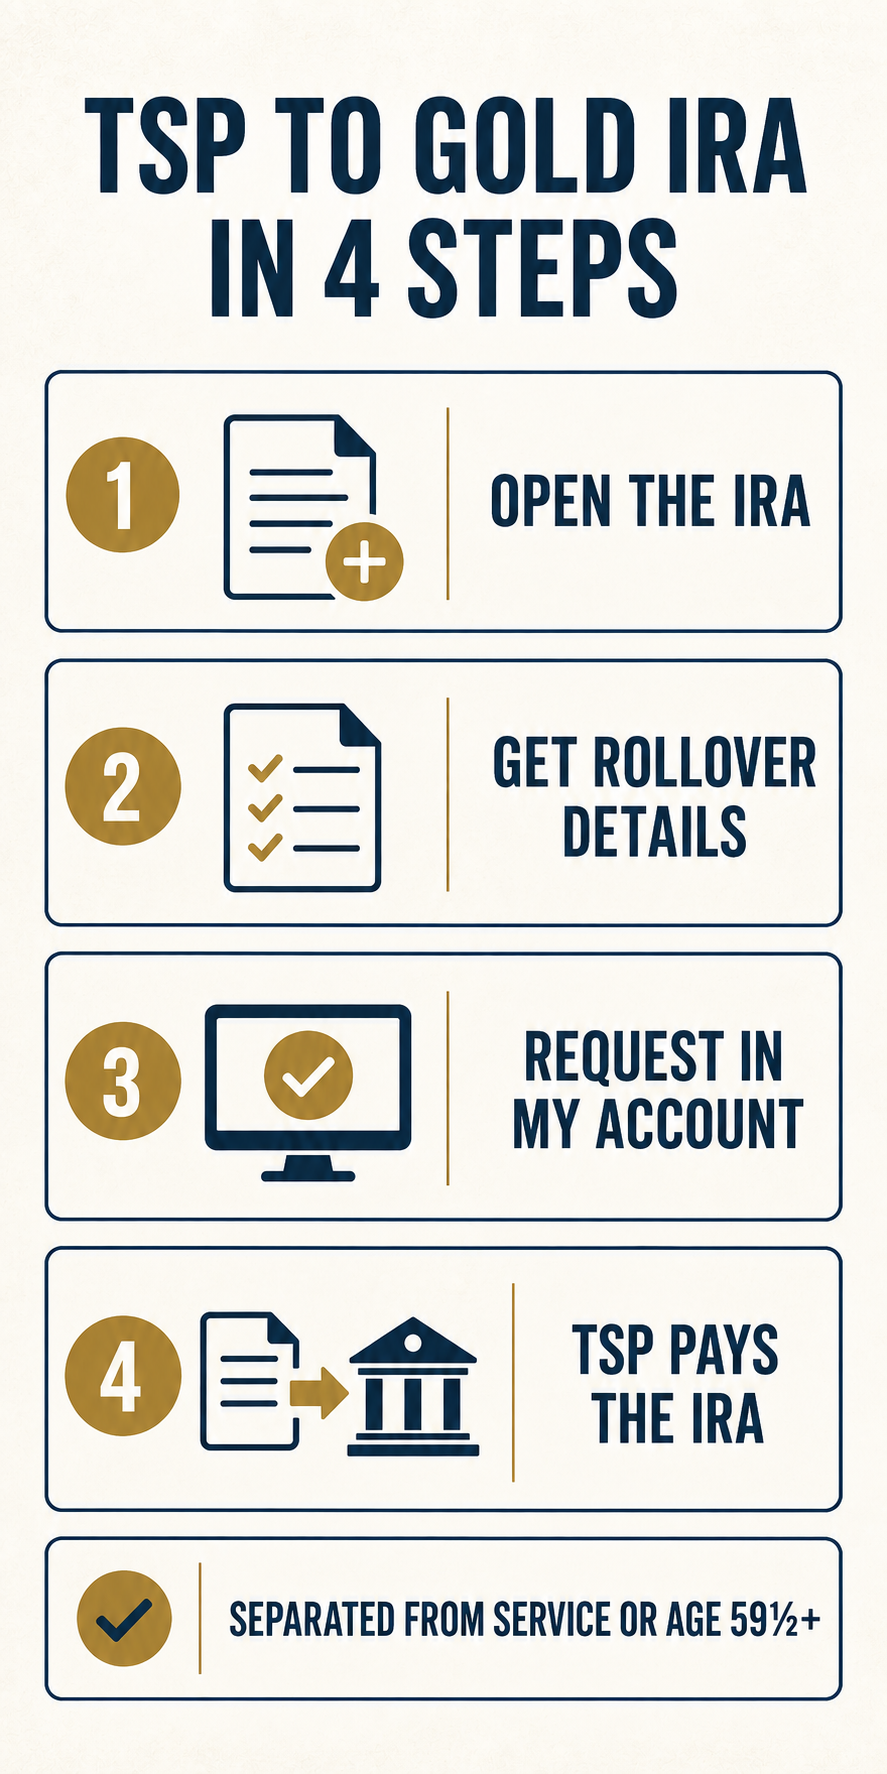
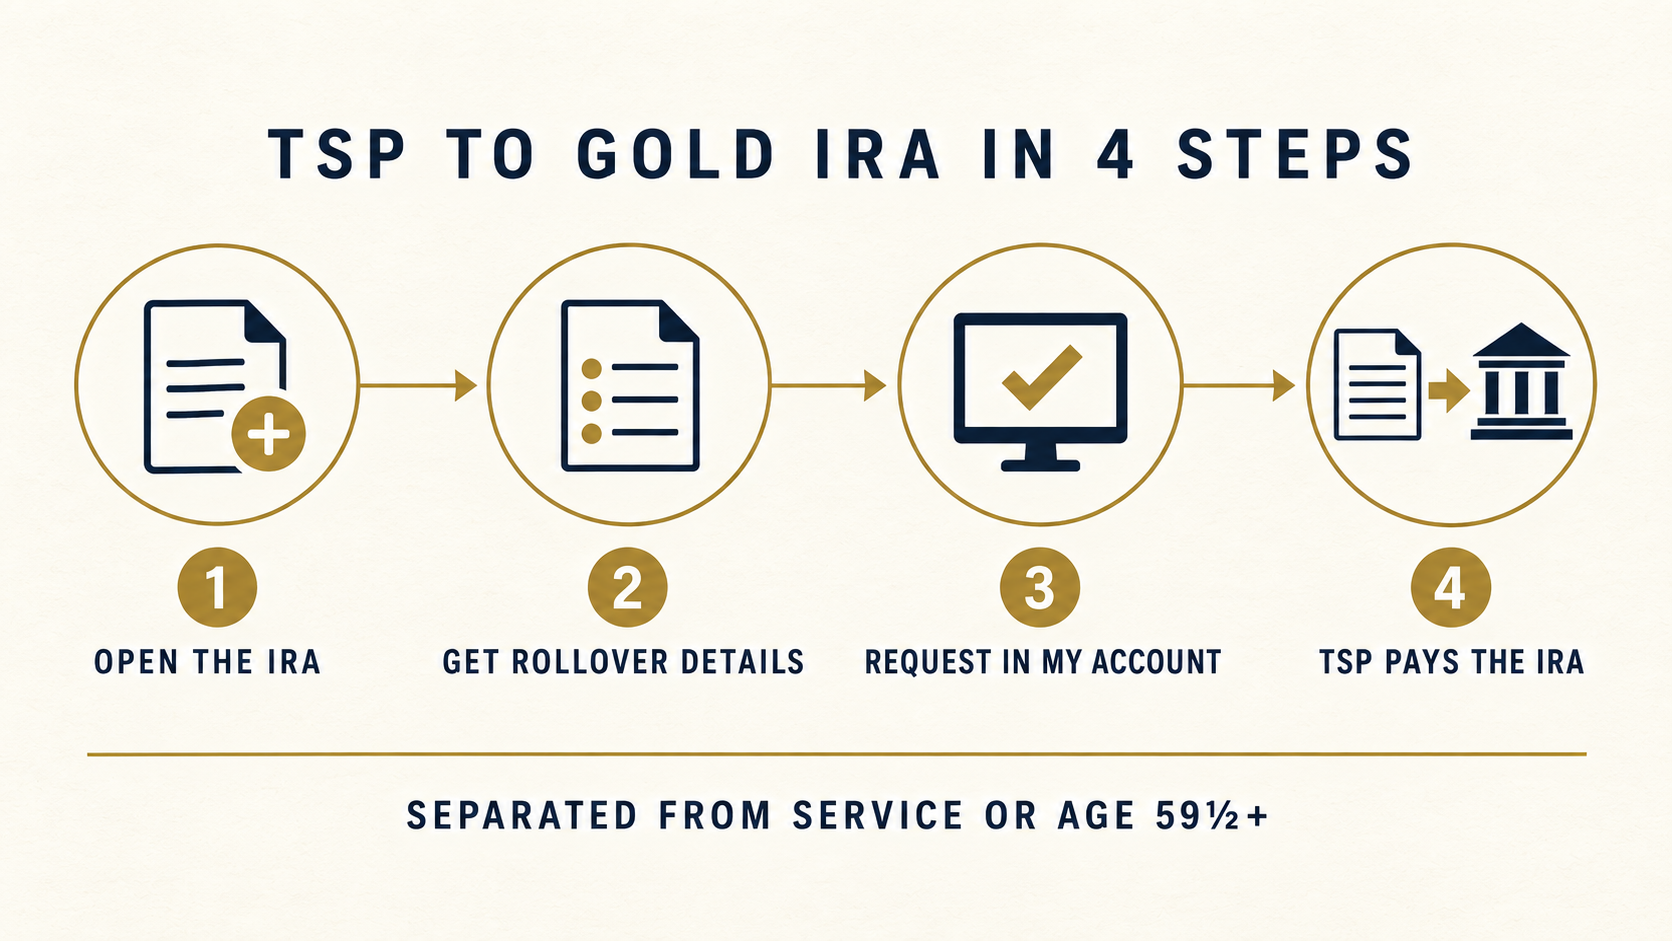
- Open the receiving IRA first. For a gold IRA, that's a self-directed IRA with a custodian that can hold physical metals. See our guide to gold IRA custodians for how to check one.
- Get the receiving custodian's rollover details. The TSP requires the receiving financial institution to certify that it will accept the funds and to provide its rollover information for your request.
- Submit the request in My Account or through the ThriftLine. The TSP says requests entered before noon Eastern time are processed that same night, and your mailing address or bank information must have been on file for at least seven days.
- The TSP pays the receiving IRA. The TSP's rollover fact sheet says rollovers are paid by U.S. Treasury check to the receiving plan or IRA.
Check every detail before you submit. The TSP is explicit that "withdrawals and distributions cannot be reversed once they've been processed."
Traditional and Roth TSP Money
Most TSP accounts hold traditional (pre-tax) money, and many also hold Roth money. The TSP treats them differently:
| TSP balance | Where it can go | Tax treatment the TSP describes |
|---|---|---|
| Traditional | A traditional IRA, an eligible employer plan, a SIMPLE IRA, or a Roth IRA | Not taxed when rolled to a traditional IRA; any part rolled to a Roth IRA "will be taxable in the current year," with no tax withheld at the time |
| Roth | A Roth IRA or a Roth account in an eligible employer plan | The TSP says "you cannot roll over Roth money to a traditional IRA" |
One Roth detail matters for planning: the TSP says the starting date for the 5-year rule for qualified Roth distributions "does not carry over" to a Roth IRA. How that affects you is a question for a tax professional.
Tax-exempt balances
Some uniformed services members have tax-exempt money from combat zone pay. The TSP says a traditional IRA must certify that it accepts tax-exempt money before the TSP can roll it over, and that it rolls over the taxable portion first. If the IRA doesn't accept tax-exempt balances, the TSP pays that portion to you directly. Ask the receiving custodian whether it accepts tax-exempt TSP money before you submit your request.
Spousal Consent
The TSP gives spouses specific rights, and they apply to rollovers:
- FERS and uniformed services, married, balance over $3,500: your spouse is entitled to a joint life annuity. For any other option, including a rollover, the TSP says your spouse must provide signed consent, electronically or on paper.
- Age-based in-service withdrawals: if you're a married FERS participant or a member of the uniformed services, your spouse must sign a consent waiver.
- CSRS, married, balance over $3,500: the TSP must notify your spouse of your distribution.
The TSP grants exceptions to these requirements "only in rare circumstances," so plan for your spouse's consent as part of the process.
Withholding: Why the Money Should Go Directly to the IRA
If the TSP pays you instead of the receiving IRA, it's an indirect rollover. The TSP says it is "required to withhold 20% of your payment for federal income taxes," and that to roll over the full amount you "must use other funds to make up for the 20% withheld" within 60 days. Our 401(k) to gold IRA rollover guide works through the same rule with a dollar example.
A direct rollover to the IRA custodian avoids withholding, which is why the TSP's process asks the receiving institution for its rollover details up front.
Watch for Sales Pitches Aimed at TSP Accounts
Federal retirement accounts attract targeted sales pitches. The SEC's investor alert on protecting TSP accounts notes that fraudsters "may direct investors to transfer money from their TSP accounts into self-directed individual retirement accounts." It describes the SEC's case against Red Rock Secured, which allegedly persuaded hundreds of TSP and other retirement plan investors to move money into self-directed IRAs to buy overpriced coins.
None of that means a TSP rollover is a bad idea. It means the checks matter more: get every cost in writing, confirm the custodian, and look up the company's record before you move money. Our guide to checking a gold IRA company lists where to look.
Questions to Ask Before You Start
The TSP (through My Account or the ThriftLine):
- Am I eligible for a post-separation or age-based in-service withdrawal now?
- Is my separation date on file, and is my address or bank information current?
- Does my spouse need to consent, and how is consent submitted?
The receiving custodian:
- Will you accept a TSP rollover, and what rollover information do you provide for the TSP request?
- Do you accept tax-exempt TSP balances?
- For Roth TSP money, do you offer a Roth self-directed IRA?
- What are all of your fees, and where will the metals be stored?
The Bottom Line
Moving TSP money into a gold IRA runs entirely through the TSP's own online process, not the receiving company's forms. You need to be separated from service or 59½ or older, a spouse may need to consent, Roth money can only go to a Roth IRA, and a processed withdrawal can't be reversed. Ask the receiving custodian for its rollover details, keep the money moving directly between institutions, and bring in a tax professional for anything specific to your situation.
Common questions
Frequently asked questions
- Can I roll my TSP into a gold IRA?
- The TSP lets eligible participants roll money into an IRA, including a self-directed IRA whose custodian holds physical metals. You must have separated from federal service, or be 59½ or older for an in-service withdrawal. The request is made in My Account or through the ThriftLine.
- Can I roll over my TSP while still working for the government?
- Only through an age-based in-service withdrawal. The TSP says these are available at age 59½ or older, up to four per calendar year, for at least $1,000 or your entire vested balance. The TSP's booklet on in-service withdrawals says you may be able to roll all or part of one over to a traditional IRA.
- Can Roth TSP money go into a traditional gold IRA?
- No. The TSP says you cannot roll over Roth money to a traditional IRA. Roth TSP money can go to a Roth IRA or a Roth account in an eligible employer plan, and the TSP notes that its Roth 5-year clock doesn't carry over to a Roth IRA.
- Do I need my spouse's consent to roll over my TSP?
- It depends on your retirement system. For married FERS and uniformed services participants with balances over $3,500, the TSP requires the spouse's signed consent for anything other than a joint life annuity, and spousal consent also applies to age-based in-service withdrawals. For CSRS participants, the TSP notifies the spouse.
Evidence
Sources
- TSP — Distributions booklet (TSPBK25, September 2026)as of 2026-09-24
- TSP — Tax Rules about TSP Payments (TSPBK26, April 2026)as of 2026-09-24
- TSP — In-service withdrawalsas of 2026-09-24
- TSP — In-Service Withdrawals booklet (TSPBK12)as of 2026-09-24
- TSP — Transferring and rolling over money fact sheet (TSPFS05, November 2023)as of 2026-09-24
- TSP — Withdrawals in retirementas of 2026-09-24
- TSP — Bulletin 19-6 (forms and the 30-day wait)as of 2026-09-24
- SEC — Protect Your TSP Account From Fraud (Investor.gov)as of 2026-09-24
- IRS — Rollovers of retirement plan and IRA distributionsas of 2026-09-24
Keep researching
Related research
- 401(k) to Gold IRA Rollover: IRS Rules, Steps and PitfallsHow a 401(k) to gold IRA rollover works under IRS rules: direct vs 60-day rollovers, the 20% withholding trap, the one-per-year rule, and mistakes to avoid.
- Gold IRA Custodians: What They Do and How to Check OneWhat a gold IRA custodian legally is, what it does and doesn't check, the fees it charges, and how to verify a custodian with the IRS, FDIC, OCC, or your state.
- How to Check a Gold IRA Company and Spot a ScamRetail metals dealers aren't federally regulated, so checking falls to you. Where to look, the red flags regulators list, and what enforcement cases found.